Insurance built around what you manufacture.
From steel and metal fabrication to food production, your processes, products and supply chain deserve a broker who asks more than your annual sales.
A specialist review from raw material to finished product.
Insurance Steel Brokers specializes in manufacturing insurance for businesses across California, with a local focus on San Diego County, Carlsbad, Vista, San Marcos, Oceanside, Escondido and the wider North County industrial community. We help owners connect premises, production, people and finished-product risks in one coordinated review.
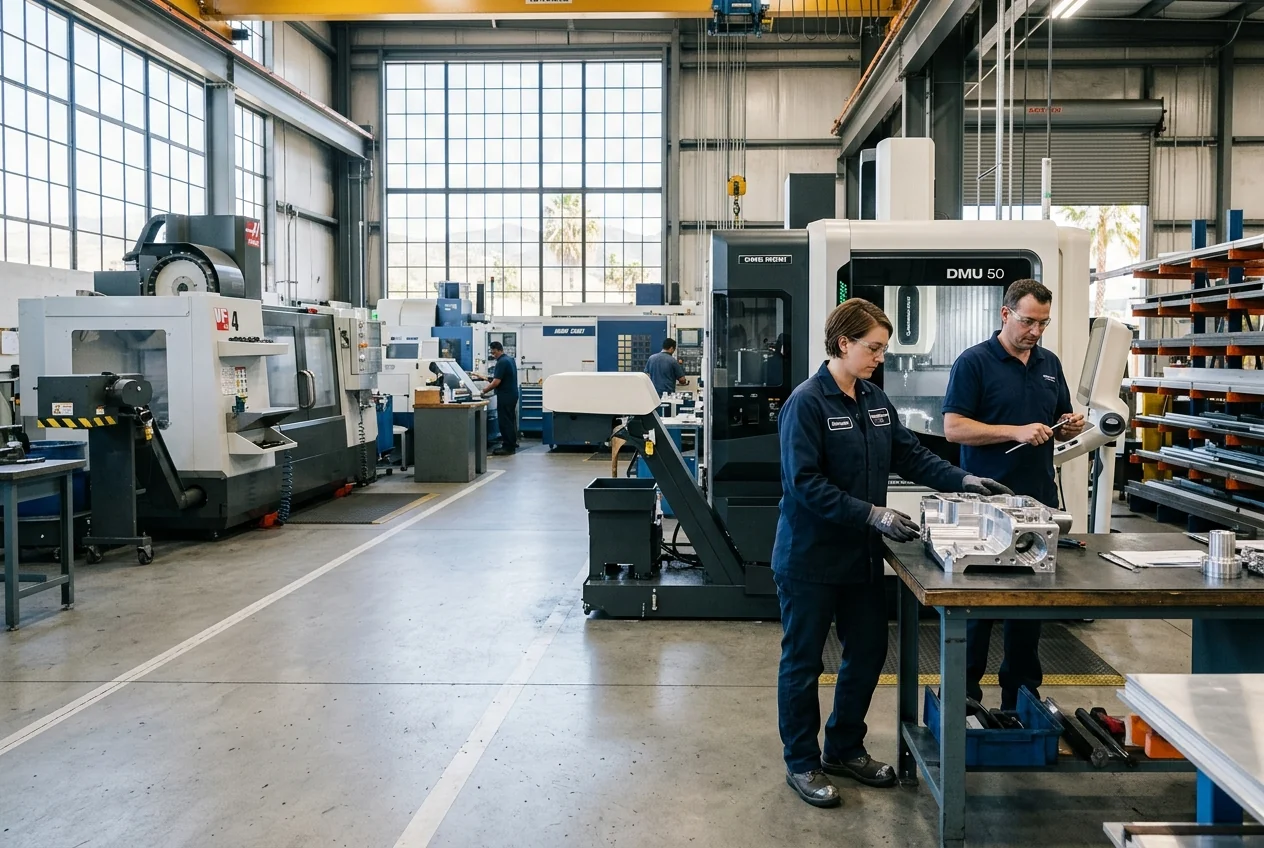
Steel businesses, metal fabricators, machine shops and food manufacturers can have very different loss scenarios. So can plastics, woodworking, packaging, electronics, assembly and other manufacturing operations. We start with what you make, how you make it and where it goes—not a promise that a standard small-business package fits every manufacturer.
Tell us whether you design, manufacture, assemble, label, distribute, import or install the product. A contract manufacturer producing to someone else’s specification still has its own exposures. Products used in vehicles, medical applications, aerospace or other critical systems may need particularly specialized underwriting.
Protect the operation, the product and the recovery.
Review allegations that a product caused bodily injury or property damage, sales territories, end uses, defense provisions and exclusions. A product guarantee and a recall policy are different matters.
Value machinery, dies, molds, raw materials and work in process. Discuss equipment breakdown, waiting periods, restoration time and dependent-property exposures rather than assuming everything is included.
Explain machine operation, fabrication, sanitation, warehousing, maintenance and office duties so payroll and classifications reflect the actual work.
Evaluate welding fumes, metal finishing, chemicals, waste, contamination and transportation-related exposures. Standard liability policies can contain important pollution exclusions.
Review shipments, customer property, off-site operations and mobile equipment. Ownership and risk-of-loss terms matter when someone else transports your product.
Discuss network-connected production, ordering systems, vendor dependencies and cyber interruption. Manufacturing downtime is not automatically covered by a property or cyber policy.
Steel, metal fabrication and machine-shop insurance.
Structural steel fabrication, ornamental metalwork, machining, cutting, forming, welding and sheet-metal work each create different underwriting questions. Describe material grades, tolerances, customer specifications, quality controls, coatings and any field installation. A shop-only policy should not be assumed to cover erection or work away from the premises.
CNC machinery, tooling, dies and molds can be costly to replace and slow to source. Discuss equipment breakdown, electrical damage, leased equipment and production bottlenecks, as well as the time needed to qualify a replacement line or subcontract production after a covered event.
Food manufacturing, processing and packaging.
Food processors, commercial production kitchens, beverage producers, bakeries and co-packers should explain ingredients, allergens, temperature controls, sanitation, traceability and labeling responsibilities. The insurance needs of a production facility differ from those of a restaurant serving meals directly to guests.
Consider spoilage, refrigeration breakdown, contamination, customer claims and the costs of a withdrawal or recall. Products liability does not automatically pay to recall, replace or dispose of your own product; product recall or contamination coverage may require a separate policy or endorsement. Availability depends on the product, controls and insurer appetite.
If you also operate a restaurant, catering service or retail kitchen, review those operations separately.
Other manufacturers deserve the same process-level attention.
We also discuss plastics, furniture and wood products, electronics assembly, packaging, consumer goods and other manufacturing risks. Do not assume that a broad industry label settles coverage for flammable materials, dust collection, heat treatment, outsourced components or a change in product design.
Share supplier and customer contracts, territories, installation work and warranties. Foreign sales, imported components, customer-owned tooling and agreements to indemnify another business can change the liability review. We can assess available markets without promising that every operation or end use is acceptable.
Business income is about the production path—not just the building.
If a single machine, utility or supplier stops production, what revenue and continuing costs are at stake? Review the covered cause-of-loss trigger, waiting period, restoration period, extra expense, sublimits and any dependent-property coverage offered.
A property claim does not automatically cover missed orders, penalties, lost market share or every supply-chain delay. Bring a realistic recovery plan, replacement lead times and seasonality to the discussion so policy limits and expectations are grounded in your actual operation.
Bring the details behind the production line.
- Products, end uses, processes and percentage of sales by activity
- Locations, building details, protection systems and equipment values
- Raw materials, work in process, finished stock and customer-owned property
- Payroll, duties, revenue, subcontractors and off-site installation work
- Quality-control, recall/traceability and safety procedures relevant to the operation
- Customer/supplier contracts, sales territories, loss history and current policies
- Downtime estimates, critical suppliers and replacement lead times
Questions worth asking.
- Do you specialize in steel and metal manufacturers?
- Yes. We review steel fabrication, metalworking, machine shops and related businesses, including their specific processes, products and installation activity. Markets and terms depend on the operation; a factory label alone does not confirm eligibility.
- Can you help food manufacturers as well as restaurants?
- Yes. We approach food processing, production and co-packing as distinct manufacturing exposures. We also specialize in restaurants, and can review businesses that combine production with food-service operations.
- Is product recall included in products liability?
- Not automatically. Liability for injury or damage to others and the costs of withdrawing your own product are different risks. Ask about available recall or contamination coverage and the triggers, limits and exclusions of the actual form.
- Do you serve manufacturers outside North County?
- Yes. Our Carlsbad team serves manufacturers across San Diego County and California. Tell us about every location, sales territory and off-site activity so the review is complete.
A local team in Carlsbad.
Serving San Diego County, North County and clients across California. Reach out before visiting so we can arrange time to discuss your questions.
Contact our Carlsbad office2870 Whiptail Loop Ste 223
Carlsbad, CA 92010888-268-7113
Monday to Saturday · 9 AM to 6 PM PST
Continue the conversation.
Connect the manufacturing review with premises, vehicles and broader business needs.
If your work extends into installation or contracting, review the trade and job-site exposures too.
Explore our food-service specialty for dining rooms, kitchens and catering operations.
Further reading.
Begin with the losses your business could face, then compare the terms—not just the names or prices—of proposed policies.
Understand the questions around employees, payroll and job duties before requesting a policy or assuming an exemption applies.
Insurance Steel Brokers · Independent insurance guidance
Talk with Nathan Norman, property & casualty
California License #0L80995
Meet Nathan NormanOfficial California resources
Coverage is subject to insurer approval, property or business eligibility, underwriting, limits, deductibles and policy terms. Examples are not promises of coverage. A quote request does not bind or amend insurance. Market availability can change.